
A Quieter Quarter, but a Stronger One
Q3 slowed the pace, as it always does. It didn’t soften the market.
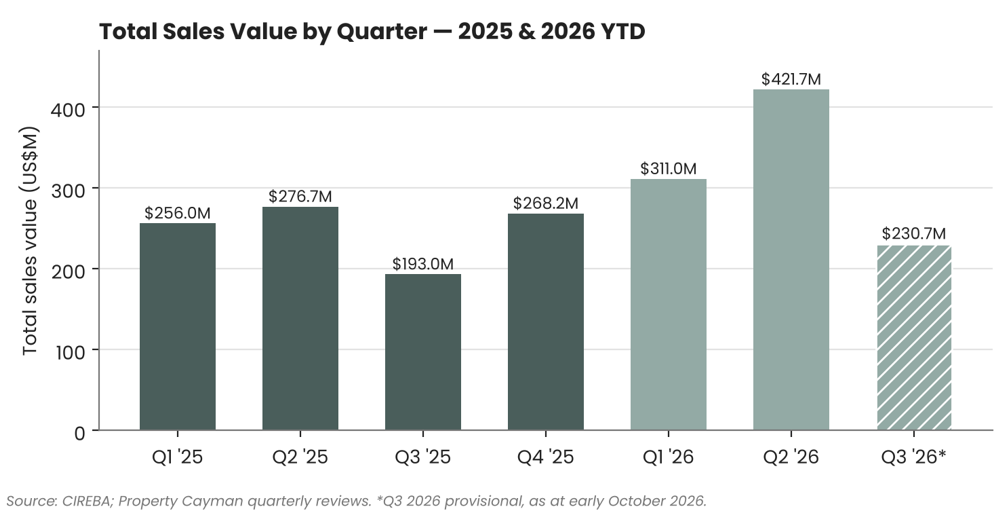
The third quarter is traditionally the quietest stretch of the Cayman property calendar, and Q3 2026 was no exception in terms of pace. In value, however, it was a different story. As we anticipated in our Q2 review, pending contracts carried through the summer: fewer transactions than in spring, but a clear step up in sales value compared with the same quarter last year.
As always, a sincere thank you to our clients, partners and community for your continued trust.
The Numbers
Fewer transactions, higher values: a pattern that has held for much of the past year.
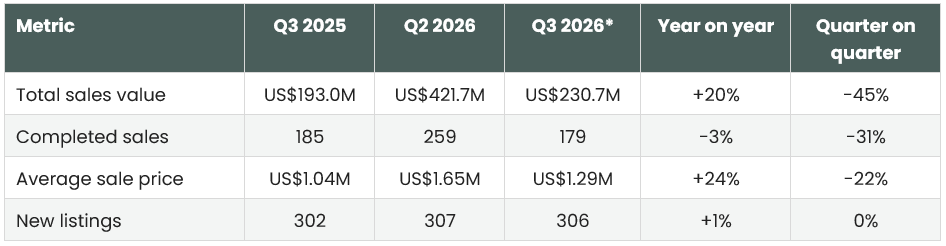
Q3 2026 recorded 179 completed sales worth US$230.7 million, 20% higher in value than Q3 2025, despite a slight decline in transactions. The average sale price rose to approximately US$1.29 million, up 24% year on year. Those comparisons use the figures published in our earlier quarterly reviews. CIREBA has since updated some historical records, including last year’s figures, so the increase is more modest on a fully updated basis. The direction, however, is the same: more value from fewer transactions.
Against Q2, the figures need context. Q2’s record US$421.7 million was lifted by the completion of pre-construction contracts at The Watermark and OneGT, agreed months or years earlier. Measured against a normal summer rather than an exceptional June, Q3 held up well. New listings, at 306, were broadly level with both Q2 and last year. Supply isn’t loosening; it’s simply holding.
Month by Month
A strong July, a steady late summer, and sellers preparing early for high season.
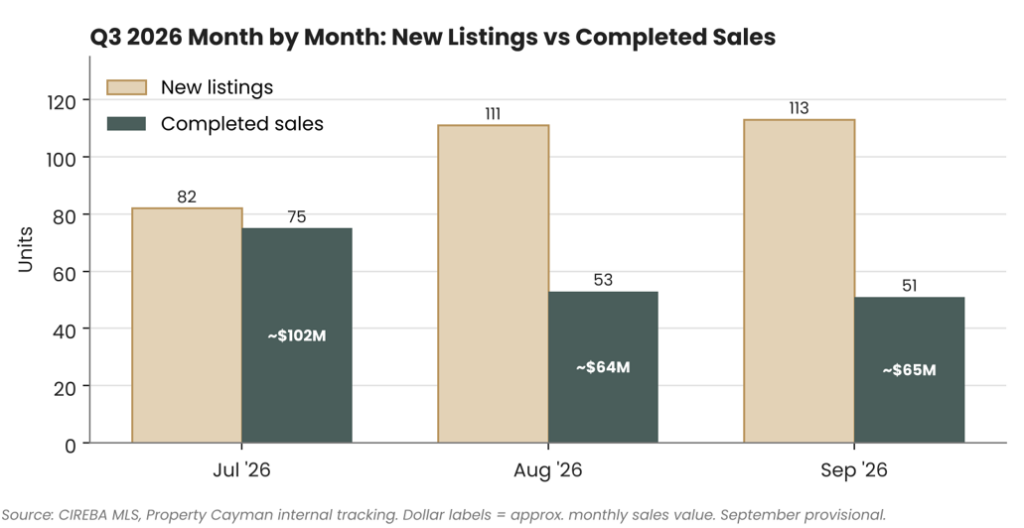
July led the quarter with 75 sales and roughly US$102 million in value, around 44% of the quarter’s total. August and September then settled at just over 50 sales and around US$64 million to US$65 million each month. Meanwhile, new listings climbed from 82 in July to 113 in September as sellers positioned themselves ahead of the November-to-May high season. Pending deals also picked up to around 50 in September, an early, if partial, signal for Q4 closings.
That isn’t a warning sign; it’s the calendar. But it does mean the coming months will reward sellers who price with discipline from day one, rather than testing the market and adjusting later once the season is already underway.
Year to Date: 2026 Against 2025
With the final quarter underway, 2026 is already approaching last year’s full-year sales value.
Using the same reporting basis as our quarterly reviews, January to September 2026 recorded approximately US$963 million across 636 sales: 33% more value than the same period of 2025, from just 4% more transactions. CIREBA’s live MLS figures include late-recorded sales and use a later cut-off date. As at 20 October, they showed US$1.08 billion across 706 sales, already 95% of 2025’s full-year total of US$1.13 billion. The two sets of figures are therefore not directly interchangeable.
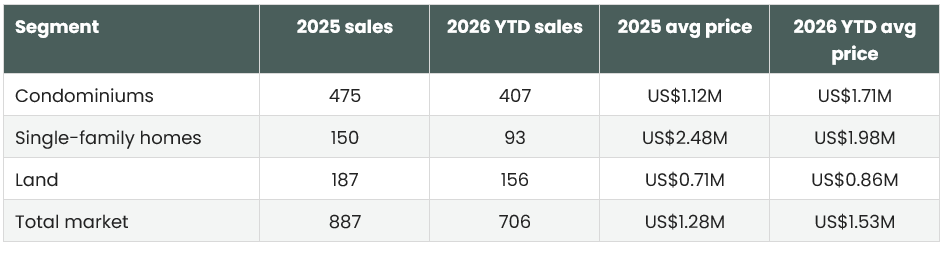
The growth is coming from what is being bought, not simply how many properties are selling. Set the large development completions aside and the underlying market looks steady rather than spectacular: the average monthly number of sales this year is close to 2025 (around 76 against 74). Condominiums have already exceeded 2025’s full-year sales value, although completions at The Watermark and OneGT account for much of the jump in average price. Single-family homes are running behind last year’s pace, possibly an after-effect of the 10% stamp duty rate on properties above US$2.4 million, which may have brought higher-value purchases forward into late 2025. On a comparable-period basis, active residential listings are broadly in line with 2025. With many properties already under contract, completed, well-located homes remain limited.
Policy and the Wider Backdrop
Worth watching, not worrying about.
There is no change to report on the Permanent Residency points framework. The immigration amendments that took effect on 1 May left it untouched, with any changes relating to real estate investment deferred to future legislation. Closer to home, the Cayman Forward findings published in July called for faster, more transparent planning decisions, with the new START taskforce charged with delivery. Housing affordability also returned to focus through the Auditor General’s September report and planning amendments supporting Government’s housing reform agenda.
Further afield, the Middle East conflict has pushed oil prices sharply higher, and in September the US Federal Reserve raised rates to 3.75%–4.00%. With the Cayman dollar pegged to the US dollar, local lending rates tend to follow, adding pressure for mortgage-reliant buyers, while rising airfare surcharges could weigh on price-sensitive visitors this winter. On the other side of the ledger, periods of global uncertainty have historically reinforced the appeal of stable, US-dollar-linked jurisdictions. The outlook for hurricane activity is another factor to watch as high season approaches.
We expect the market to keep moving at different speeds by price tier. The cash-funded upper end looks best placed. Entry-level property remains supported by a structural shortage of housing, though higher financing costs may thin the buyer pool. Investment-led mid-tier condos, where rental returns haven’t kept pace with prices, are the segment we’ll watch most closely. We’d expect a more considered pace there, not a correction.
Sources: gov.ky (Immigration Reform; Cayman Forward, 10 July 2026); Office of the Auditor General, September 2026; US Federal Reserve, 16 September 2026; NOAA CPC ENSO update, 8 October 2026; Cayman Islands Public & Affordable Housing Policy, 2026.
Looking Ahead
Q4 has historically been the stronger end of the year and sets the foundation for Q1. The ingredients are in place for that pattern to repeat. For buyers, the coming weeks offer the widest choice of new listings since spring, ahead of high-season competition. For sellers, realistic pricing at launch matters more than ever. For investors, Cayman’s fundamentals, including tax neutrality, stability, quality of life and constrained supply, remain intact. Income-focused buyers will simply want to run the numbers carefully.
Final Thoughts
Q3 did what Q3 usually does: it slowed the pace. What it didn’t do was soften the market. The market is not cooling; it is settling into a more mature, more selective rhythm, one that rewards clear thinking, honest pricing and good advice.
If you’d like to talk through what this means for your own plans, I’m always happy to have that conversation.
Figures are CIREBA-wide market data as compiled by Property Cayman and are not limited to Property Cayman’s own transactions. Q3 2026 figures are provisional as at early October 2026 and may shift modestly as CIREBA records are completed. Year-on-year and quarter-on-quarter comparisons use the figures published in our earlier quarterly reviews. MLS data is submitted by Members and is not independently verified by CIREBA. This report is a broad overview and not investment advice. Property Cayman Ltd. is a member of CIREBA.
Access to exclusive content
Sign Me upEvery week, we’ll send you exclusive content information to help you along your property journey. Don’t worry – good stuff only.

